

Dollarbird Pro analysis by Appwee
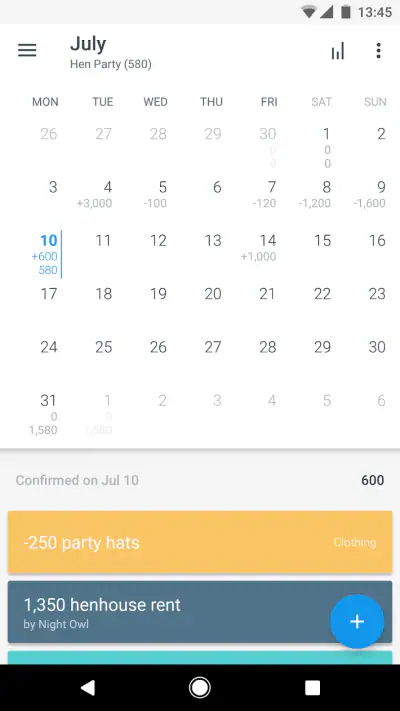
I tend to judge finance apps by one simple question: do they make the next money decision easier, or do they merely turn record-keeping into another chore? Dollarbird Pro takes an interesting route. Instead of treating personal finance as a list of transactions, it presents money through a calendar, so I can see when income and expenses are expected to land. That makes it especially appealing when timing matters as much as totals.
Developed by Dollarbird Apps SRL, this free finance app is aimed at everyday budgeting rather than professional accounting. Its store summary describes it as a personal finance calendar with a spark of AI, while the short description identifies the product as Dollarbird Pro. The app is rated for Everyone, runs on Android six and later, and its current version is 6.2.2. Those details matter because the experience feels designed for people who want a visual plan for upcoming cash flow, not a complicated ledger full of accounting terminology.
How the calendar approach feels in daily use
When I open a conventional budgeting app, I usually start by checking categories or a monthly spending total. With Dollarbird Pro, my attention goes first to the dates. That small change in perspective is the app’s central strength. A rent payment, salary, subscription, grocery trip, or planned transfer becomes part of a timeline rather than an isolated entry. I can then ask a more useful question: “How much will I have available after these events?”
This is a particularly practical approach for anyone whose balance rises and falls sharply during the month. A monthly total can look healthy while still hiding a difficult week before payday. A calendar makes that gap easier to notice. I can place recurring commitments around the dates they actually happen and see how a cluster of bills affects the rest of the month.
The visual format also makes planning less abstract. Instead of promising myself that I will “spend less,” I can look at the days ahead and decide whether a purchase fits between known obligations. That is a more concrete habit, especially for users who find category-based budgeting too detached from real life.
There is a useful distinction here between recording what already happened and planning what is likely to happen. Dollarbird Pro is most convincing when I use it for both. I can enter a transaction after paying a bill, but I can also plan a future expense before it leaves my account. The second use is where the calendar earns its place on my phone.
A realistic month with the app
Imagine that I receive my salary near the beginning of the month, pay housing costs a few days later, and have several smaller subscriptions spread across the following weeks. I would enter the income on its expected date, add the fixed payments, and then place flexible spending where I expect it to occur. Before agreeing to an expensive dinner or an online purchase, I could check the remaining stretch of the calendar rather than relying on memory.
The same workflow helps with irregular expenses. A school cost, annual renewal, car repair, or planned trip can be added ahead of time. Even if the amount changes later, seeing the event on the calendar gives me a prompt to revisit the plan. That is more useful than discovering the expense only after the account balance has already fallen.
My practical advice is to begin with only the events that influence decisions: income, housing, utilities, debt payments, subscriptions, and major planned purchases. Filling the calendar with every tiny purchase immediately can make setup feel heavy. Once the main cash-flow picture is visible, I would add detail gradually. The app works best when it remains a planning tool rather than becoming a second bank statement.
Where its “AI” angle fits
The app presents itself as having a spark of AI, but I would not choose it expecting an automated financial adviser. The useful way to approach that wording is as an added layer around a calendar-based money system, not as a replacement for checking entries or making decisions. I would still verify dates, amounts, and recurring items myself.
That distinction is important for anyone hoping to connect the app to a bank and have everything handled automatically. Dollarbird Pro’s appeal is its deliberate, user-guided planning style. If I want to understand my upcoming commitments, that can feel empowering. If I want a completely hands-off feed of categorized transactions, a bank-linked budgeting service may suit me better.
In practice, I see the AI reference as something to watch rather than the main reason to install the app. The calendar is the part with an immediately understandable benefit. The smarter assistance will only be valuable if it reduces entry work without making assumptions that I then have to correct.
The current product and its evolution
The app has been available since July 31, 2017, so it is not a brand-new experiment. Its current version, 6.2.2, suggests an established product that has continued to receive updates. That history is reassuring for someone who wants a finance tool to remain usable over time, although an established app can also carry design decisions that newer competitors have avoided.
I would describe the current state as focused rather than overloaded. The product identity is clear: a personal finance calendar with planning at the center. It does not need to imitate every feature found in a full banking dashboard. The benefit is that the main idea is easy to explain and easy to test. Add several upcoming events, review the resulting timeline, and you quickly discover whether this way of budgeting suits you.
At the same time, version information should not be confused with a promise about future features. A newer release can improve stability or refine existing workflows without changing the fundamental model. I would therefore install it for the calendar method that exists now, not for assumptions about what later updates might add.
What existing users may notice over time
People who already use the app will probably get the most value from treating each update as a reason to review their routine, not simply as something to install and forget. With a finance calendar, old recurring entries can quietly become inaccurate. A subscription may change, a payment date may move, or an income pattern may no longer match the original plan.
My recommended maintenance routine is simple: at the start of each month, scan the calendar for recurring commitments; after a major life change, adjust future events; and before making a large purchase, look beyond the current week. This turns the app into a forward-looking habit instead of a historical archive.
That habit also reveals a trade-off. Manual planning gives me control over the assumptions, but it asks me to stay involved. If I stop entering changes, the calendar can become confidently wrong. No visual forecast is better than the information behind it, so users should resist the temptation to treat planned amounts as guaranteed balances.
Useful workflows beyond basic expense entry
One less obvious use is testing alternative plans. I can create a conservative version of the month by entering a lower expected income or a higher estimate for a variable bill, then compare that mental scenario with my normal plan. This is not a substitute for formal forecasting, but it is a practical way to see whether a purchase still looks comfortable under less favorable conditions.
Another helpful workflow is separating certainty from intention. Fixed bills deserve precise dates and amounts. Flexible items such as entertainment, dining, or shopping can be entered as planned allowances rather than treated as unavoidable facts. That distinction prevents the calendar from making optional spending look as rigid as rent.
I also like the idea of using the calendar before a trip or a busy season. Instead of waiting for several unusual transactions to appear, I can place transport, accommodation, meals, and expected extras on the relevant dates. The result is not just a trip budget; it is a view of how the trip may affect ordinary bills before and after it.
For couples or households, the calendar can support a conversation even when it is not being used as a shared accounting system. One person can explain why a particular week feels tight, while the other can see the timing of the commitments. The limitation is that both people need a clear agreement about who enters changes and which amounts are estimates.
Where the experience may become frustrating
The strongest limitation is also the app’s defining choice: a calendar is not automatically the best interface for detailed analysis. If I want deep category reports, extensive charts, investment tracking, tax preparation, or a complete net-worth picture, I would look elsewhere. Dollarbird Pro can help me plan spending, but it should not be mistaken for a full replacement for every financial tool.
Manual input can also become tiring for users who expect automatic synchronization. Someone with many accounts, frequent card purchases, or complicated household finances may prefer an app that imports transactions and categorizes them in the background. Dollarbird Pro’s hands-on approach is useful when I want to make deliberate plans, but it creates more responsibility when my financial life is busy.
The average rating is 3.3 from around 592 ratings, with around 128 written reviews. I read that as a sign to approach the app with realistic expectations rather than assuming it will satisfy everyone. A mixed reception is understandable for a product built around a particular workflow: people who enjoy calendar planning may find it refreshing, while users looking for automatic bank aggregation may feel that too much work remains.
There is also a learning curve in deciding how much to enter. If I record every coffee, small purchase, and minor adjustment, the calendar may become cluttered. If I record too little, the forecast becomes vague. The best balance depends on the decisions I want the app to support. I would use it for meaningful cash-flow events first and add transaction detail only when that detail changes my behavior.
Free access, paid extras, and the practical decision
Dollarbird Pro is free to install, which makes it easy to test without committing money at the outset. It includes in-app purchases ranging from $7.99 to $79.99 per item. Because the purchase range is broad, I would inspect the exact option shown in the app before paying and decide whether the additional value matches the way I actually budget.
My test would be straightforward: use the free experience long enough to build a normal month, include at least one irregular expense, and see whether I return to the calendar before making decisions. If I do not develop that habit, a paid upgrade is unlikely to solve the underlying problem. If the timeline becomes part of my weekly routine, then paying for expanded capabilities may be easier to justify.
I would also compare the cost with the value of alternatives. A spreadsheet offers total control and can be free, but it requires more setup and rarely feels as immediate on a phone. A banking app may show actual balances with less manual work, but it may not make future commitments as visible. A category-focused budget app can provide stronger reporting, while Dollarbird Pro may be better for timing. The right choice depends on whether my main difficulty is understanding categories, importing transactions, or surviving the gaps between paydays.
Who should use it and who should skip it
I would recommend this app to someone paid on a regular schedule who wants to see the month as a sequence of financial events. It is also a good candidate for people who repeatedly forget annual costs, underestimate the effect of clustered bills, or need a gentle visual reminder before spending.
It may suit freelancers and people with uneven income too, provided they are willing to enter realistic estimates and update them. In that situation, the calendar can help compare expected income dates with obligations. The user must be especially careful not to treat projected income as money already available.
I would skip it if my priority is automatic account importing, detailed investment management, business bookkeeping, or highly granular analytics. I would also avoid relying on it as my only financial record if I need formal documentation. A calendar can improve awareness, but it is not the same as a bank statement or accounting system.
What I would watch in future updates
For future development, I would pay attention to whether the AI element reduces repetitive planning without weakening user control. Helpful suggestions would need to be transparent enough for me to understand why a date or amount was proposed. In finance, convenience is valuable only when corrections are easy and assumptions are visible.
I would also watch how the app handles the tension between planning and actual spending. The most useful evolution would connect those two views clearly: planned events should remain easy to edit, while completed transactions should not blur the difference between an estimate and a confirmed payment. That distinction is central to the app’s usefulness.
Another area worth watching is flexibility for different household arrangements. Shared planning, irregular income, and multiple financial goals all place pressure on a calendar model. Improvements here would matter more to me than adding decorative features, because they would expand the situations in which the app can remain accurate without becoming burdensome.
My final take on the calendar method
After looking at the product as a daily budgeting companion, I see Dollarbird Pro as a focused solution rather than an all-purpose finance suite. Its best idea is simple but meaningful: money becomes easier to manage when I can see its timing. That view helps me prepare for crowded weeks, plan irregular expenses, and make purchases with the next few dates in mind.
The trade-off is equally clear. I have to participate. Users who want automatic collection and extensive reports may be happier with a bank-connected alternative or a more analytical budgeting platform. Users who want a calm, visual way to plan cash flow may appreciate the restraint.
For me, the deciding test is whether the calendar changes a decision. If it helps me delay a purchase, prepare for a large bill, or notice a difficult week before it arrives, it is doing something useful. Since it is free to try and available to Everyone on compatible Android devices, I think it is worth testing for that specific purpose. Choose it for forward-looking cash-flow planning, not for features it was never designed to replace.
Gallery
Dollarbird Pro Pros and Cons
- Clear calendar view makes upcoming bills and income easy to track.
- Supports recurring transactions for regular expenses and payments.
- Custom categories help organize spending around personal priorities.
- Cloud syncing keeps financial data available across supported devices.
- Useful cash-flow forecasts can help prevent unexpected shortfalls.
- Requires consistent manual entry unless transactions are imported.
- Advanced budgeting tools may feel limited for detailed financial planning.
- Subscription cost may not suit users seeking a completely free tracker.
- Shared finances can be less convenient than dedicated household budget apps.
- Currency and regional banking support may vary by location.
Dollarbird Pro Frequently Asked Questions
What is Dollarbird Pro used for?
Dollarbird Pro is a personal finance and budgeting app designed to help you track income, expenses, bills, and upcoming financial commitments in one calendar-based interface. Instead of only showing past transactions, it lets you look ahead and estimate your future balance. This can make it easier to plan recurring payments, organize spending, and avoid surprises when several bills are due around the same time.
How does the calendar-based budgeting system work?
Dollarbird Pro organizes your finances by date, allowing you to add transactions to specific days and review how your balance may change over time. You can record income, everyday purchases, subscriptions, and scheduled bills, then use the calendar to identify periods of higher spending. The forecasting feature is particularly useful for planning ahead, although its accuracy depends on keeping your entries complete and up to date.
Can I use Dollarbird Pro to manage shared or family finances?
Dollarbird Pro may be useful for households, couples, or small groups that want to coordinate a shared budget, depending on the collaboration features available in the current version. Shared financial planning can help everyone see expected bills and spending categories in one place. Before downloading, check the app’s latest store description to confirm whether shared calendars, synchronization, invitations, or multi-user access are included in your subscription.
Does Dollarbird Pro connect directly to my bank account?
Users should not assume that Dollarbird Pro automatically imports transactions from every bank or financial institution. Many calendar-based budgeting apps rely primarily on manual entry, while some versions or regions may provide additional synchronization options. Review the current app listing and privacy information before installing. If automatic bank connections are unavailable, you will need to enter purchases and income yourself for reliable forecasts.
Is Dollarbird Pro free, and are there any privacy concerns?
Dollarbird Pro may require a purchase, subscription, or in-app payment for premium tools, depending on the platform and the version offered in your region. Check the Google Play Store or Apple App Store page for the current pricing and trial conditions before downloading. Because the app handles sensitive financial information, also read its privacy policy to understand what data is stored, synchronized, or shared.














